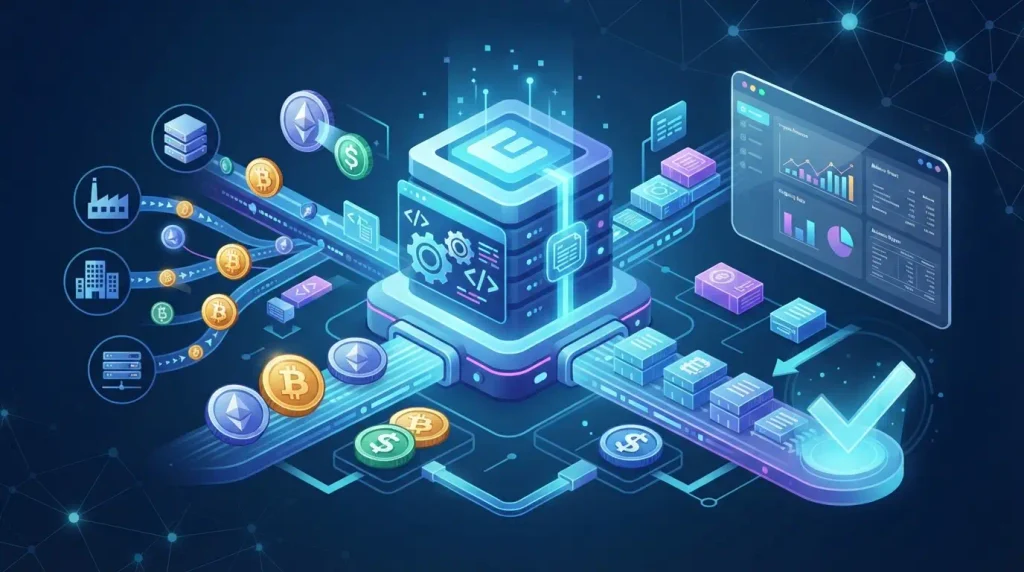
B2B crypto processing is useful only when the commercial invoice, payment instruction and financial close-out describe the same event. A transfer may settle quickly, but the business still needs a clear answer to what was paid, whether the expected conditions were met and when the receivable can be closed.
Why B2B needs more than a receiving address
A B2B payment carries contract terms, an agreed amount, a due date, a payer identity and a service or product reference. Replacing a bank instruction with a wallet address does not remove those details. It makes them more important, because a transfer without a reference can be difficult to match later. The payment workflow should therefore start from the commercial obligation, not the asset selected for settlement.
Define the states before configuring a payment link
| Status | Meaning for the customer | Meaning for finance |
| Created | Payment instructions are available. | An open receivable exists. |
| Observed | The transfer has been seen. | Do not yet assume the invoice is closed. |
| Confirmed | The required transaction condition was met. | Apply the review and fulfilment policy. |
| Available | The payment has completed the business workflow. | Record the settlement treatment. |
| Exception | Further action is required. | Assign an owner and preserve evidence. |
Make expiry a commercial rule
Expiry tells the customer how long an amount and instruction are valid. It should reflect the company’s contract, pricing and fulfilment rules, not be an unexplained timer. When a transfer arrives late, staff should know whether to issue a new instruction, review the payment manually or apply a defined adjustment. Consistency matters more than pretending that every exception can be automated.
Build a close checklist
- Match the incoming event to the invoice or order reference.
- Compare expected and received amounts using the documented policy.
- Confirm the applicable payment and review status.
- Record any conversion, withdrawal or treasury decision.
- Preserve the final evidence in the accounting close-out record.
Keep treasury choices explicit
Accepting a digital asset and deciding to retain, convert or withdraw it are separate actions. Finance should document which balances can remain exposed, who can authorize a conversion and how the result is recorded. This avoids a common gap in which operations see a completed payment while treasury and accounting cannot explain the value that later moved.
Measure the process, not just payment volume
Useful measurements include time from invoice creation to usable funds, first-pass reconciliation rate, frequency of mismatched instructions and support contacts per completed payment. These indicators reveal whether the workflow is genuinely reducing operational work. A payment rail that increases revenue but creates untraceable exceptions is not yet a mature B2B process.
Conclusion
A reconciled B2B payment lifecycle connects contract terms, a precise instruction, visible states, treasury decisions and accounting evidence. That is the practical standard for judging whether crypto processing fits a finance operation.
Match payment states to B2B commercial records
B2B payments often relate to invoices, contracts, account managers and negotiated terms. The payment workflow should preserve the commercial reference that allows finance to match a received amount to an obligation. Without that link, teams may have a technically successful payment but still spend time manually identifying why it arrived.
| Control point | Purpose |
| Invoice reference | Connects payment to a receivable. |
| Amount tolerance | Defines when a variance needs review. |
| Payment status | Prevents early delivery or fulfilment decisions. |
| Close-out record | Supports reconciliation and customer follow-up. |
Design for exceptions from the start
Plan for duplicate attempts, partial payment, missing reference, late confirmation and a customer who needs a clear next step. Define whether a case belongs to support, finance or operations, and retain the information needed to resolve it without asking the customer to recreate history.
- Create a stable invoice and payment reference.
- Set the allowed amount and timing boundaries.
- Use clear states for received, under review and reconciled.
- Route unmatched payments to a named owner.
- Review recurring exceptions for process improvements.
Practical takeaway
B2B crypto processing is operationally useful when payment data fits the billing and reconciliation model that the business already relies on.
Separate commercial acceptance from accounting close
A customer may believe an invoice is paid at a different moment from the one at which finance can complete its records. Define these states explicitly. Commercial teams need a clear rule for service delivery; finance needs matching evidence; support needs a responsible way to explain an in-progress payment. When the states are distinct, the company can manage timing without making contradictory promises.
Useful B2B operating metrics
Review the share of payments matched automatically to an invoice, recurring variance reasons, average age of unmatched items and the volume of support cases requiring finance intervention. These measures reveal whether the payment process fits the billing model or simply creates a new reconciliation queue.